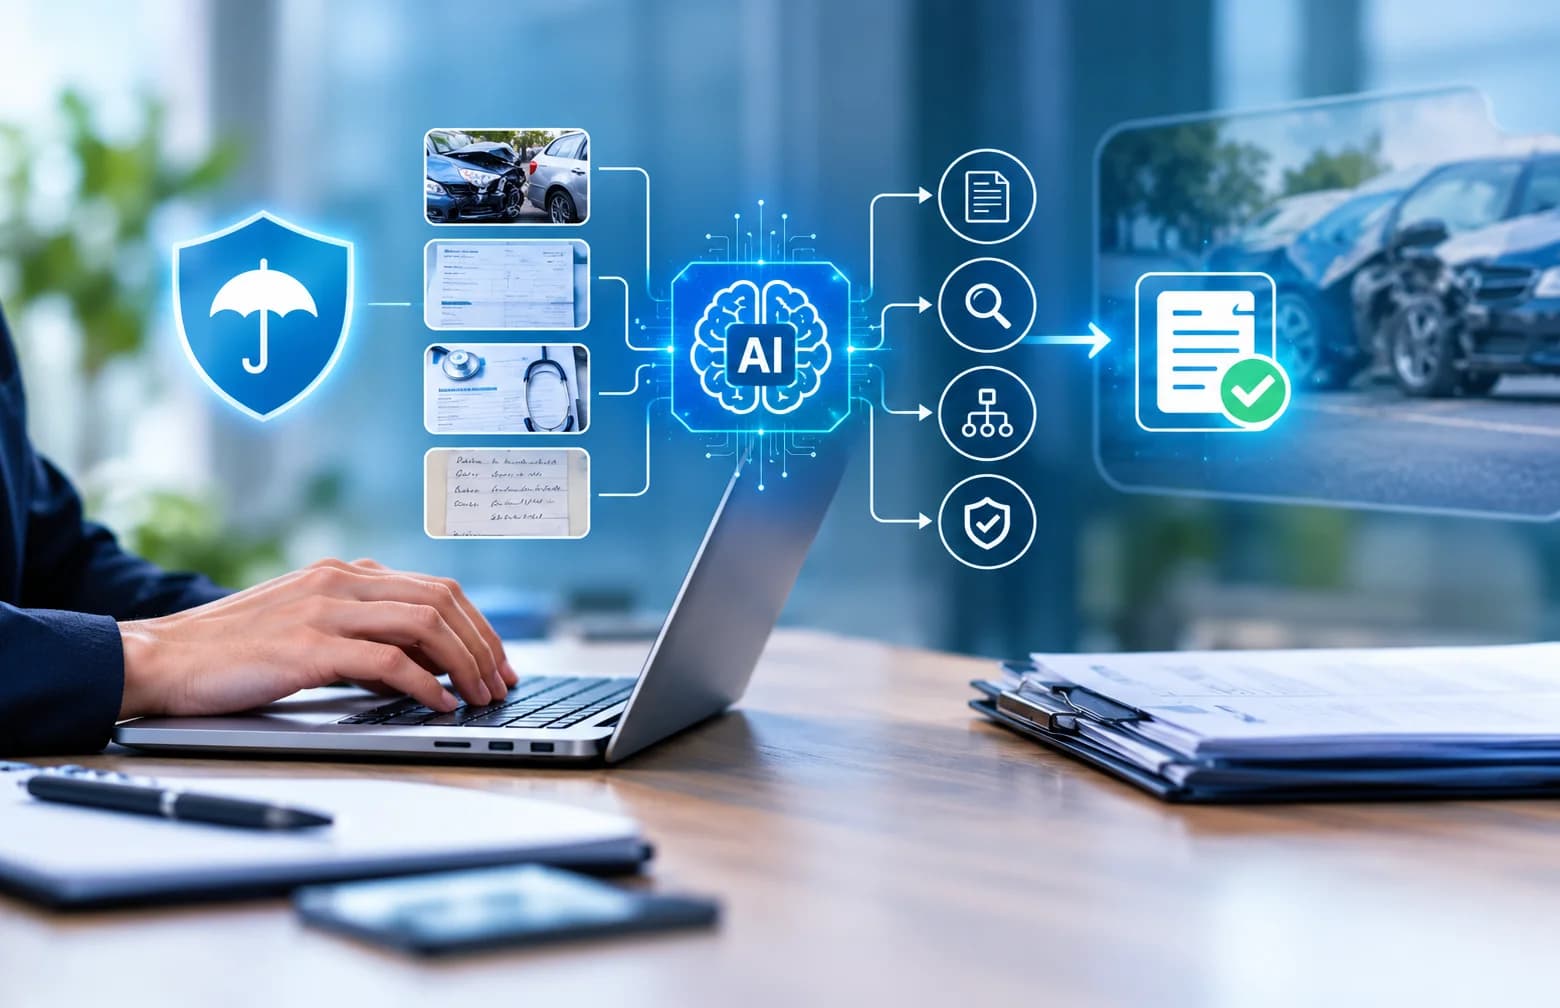
The claims function has always been where the promise of the business meets reality. Premiums are easy to celebrate. Claims are where a customer finds out whether you meant what you sold them.
For most of those years, "automation" meant a rules engine bolted onto a green-screen system and a lot of people re-keying data from PDFs. It helped a little. It never changed the economics. What is different now is that AI-powered insurance claims automation can read, classify, judge and route work that used to need a human at every step. It cuts cycle times from weeks to days, and it could also fail expensively when it is treated as a software purchase rather than an operating change. Let's cover both sides.
Why claims is the right place to start with AI
Claims typically represent the largest cost line in an insurer's business, often 70 to 80 percent of premium once you add loss adjustment expense. It is also the most manual part of the value chain. Every claim carries unstructured data: photos, repair estimates, medical records, police reports, emails, handwritten notes. Traditional systems could store these. They could not understand them.
That is the gap AI closes. Modern models read documents, extract the facts that matter, compare them against policy terms, and flag what needs a person. That is the heart of AI insurance claims processing: turning unstructured information into structured decisions, quickly and consistently.
The benefits that actually show up on the P&L
Vendors love to quote enormous percentages. Here is what holds up in real programs.
Faster cycle times.
Straightforward claims, such as windshield glass, minor auto damage, low-value property and routine outpatient claims, can move from first notice of loss to payment in hours instead of days. Customers remember speed far longer than they remember price.
Lower loss adjustment expense.
When straight-through processing handles 30 to 50 percent of simple claims, adjusters spend their time on complex files. You do not necessarily reduce headcount. You stop growing it as volume grows, which is the more realistic win.
Better consistency.
Two adjusters reading the same file will occasionally reach different conclusions. Well-governed models apply the same logic every time, which reduces leakage and complaints.
Improved fraud capture.
Pattern detection across thousands of claims finds things no individual adjuster will ever see.
Happier customers and staff.
People forget this one. Adjusters spend less time on data entry and more on judgment and empathy, which is why most of them joined the profession.
Core use cases worth your attention
1. Intelligent intake and first notice of loss
Claims often go wrong at the start. A customer calls, a call-center agent captures half the details, and the file is incomplete before anyone looks at it. AI-driven intake, whether through chat, voice or mobile app, collects structured information, asks follow-up questions in context, and validates coverage in real time. A cleaner start means fewer touches later.
2. Document extraction and classification
This is the unglamorous workhorse. Natural language processing and computer vision pull data from invoices, medical bills, estimates and ID documents, then classify and attach them to the right claim. It is usually the fastest return on investment because the manual effort it replaces is so large.
3. Triage and routing
Not every claim deserves the same treatment. AI scores complexity, severity and likely cost at intake, then routes: simple claims to straight-through processing, moderate ones to a junior adjuster, and complicated or litigated ones to a senior specialist. Good triage alone can change an operation's throughput.
4. Damage assessment from images
In auto and property, computer vision estimates damage from photos and video taken by the customer. People were skeptical of this a decade ago. Today it is genuinely useful for initial estimates, especially after catastrophe events when you have thousands of claims and not enough adjusters to inspect them.
5. AI-powered fraud detection
This is where the technology earns its keep. AI-powered fraud detection looks for anomalies across claim data, provider behavior, network relationships, image metadata and language patterns. It can spot a repair shop whose invoices look suspiciously alike, or a cluster of claims linked by phone numbers and addresses. One caution from experience: a fraud score is a reason to look closer, not a reason to deny. Treat the output as a referral to your special investigations unit, and keep a human in the decision.
6. Subrogation and recovery
Many insurers leave money on the table because no one has time to identify recovery opportunities. AI can scan claim notes and documents to surface subrogation potential that would otherwise go unnoticed.
Automation is more than the model: the workflow around it
Here is where we see most projects stumble. A clever model dropped into a broken process produces a faster broken process. Insurance workflow automation is what connects the intelligence to the work: task assignment, approvals, communications, payments, reserves and audit trails.
That is why your choice of claims management system software matters. If your core platform is a closed system with no real APIs, you will spend more on integration than on the AI itself. Modern platforms are modular and event-driven, which lets you add intelligence step by step. Legacy cores can still work, but you will usually wrap them with an orchestration layer rather than ripping them out. Replacing a core system is a multi-year, high-risk effort that most carriers should avoid unless they have no other choice.
The same discipline applies in health. Payers and providers dealing with adjudication, prior authorization and medical coding need partners with healthcare software development services experience, because HIPAA, clinical data standards and explainability expectations are more demanding than in most lines of business.
How to implement: a roadmap that has held up
The good implementations share the same shape.
Step 1: Pick one line and one problem. Start with something measurable, such as low-value auto claims or document intake for a specific product. Resist the urge to boil the ocean. A narrow win builds credibility for everything that follows.
Step 2: Fix your data first. Models are only as good as the history they learn from. Audit your claim data for gaps, inconsistent coding and bias. This step is tedious and nobody wants to fund it, and it determines everything downstream.
Step 3: Decide the human-in-the-loop rules up front. Define which decisions the system can make alone, which need review, and which are always human. Set confidence thresholds and revisit them monthly.
Step 4: Build for integration, not novelty. Your solution has to talk to your policy admin, claims, payments, document and CRM systems. Whether you buy or build, ask early about APIs, security and scalability. This is where experienced software development services teams save you from surprises, and where a specialist in fintech software development brings real value, since payments, ledgers and regulatory controls overlap heavily with claims.
Step 5: Pilot in parallel. Run the AI alongside your current process for a few weeks. Compare outcomes. Let adjusters challenge the results. Their pushback will teach you more than any dashboard.
Step 6: Monitor and retrain. Models drift. Fraud patterns change, repair costs move, and new claim types appear. Plan for continuous monitoring, not a one-time launch.
Build, buy or partner?
There is no universal answer. Buying a packaged product gets you speed and proven features, but you accept the vendor's roadmap. Building gives you differentiation and control, but demands data science, engineering and MLOps talent that many carriers cannot hire or keep. Most of the organizations we advise land in the middle: a platform for commodity capabilities and custom work for the parts that give them an edge. If you go that way, choose AI development services partners who understand insurance, not just machine learning. Someone who knows what a reserve, a coverage position or a reservation of rights is will save you months of translation.
The risks nobody should skip past
Regulation and explainability.
Regulators in many jurisdictions expect you to explain automated decisions that affect customers. If you cannot say why a claim was denied or flagged, you have a compliance problem. Build explainability in from the beginning.
Bias.
If historical decisions reflected unfair patterns, models can learn and amplify them. Test regularly across customer segments.
Over-automation.
Customers in distress, such as after a house fire, a serious accident or a death, do not want a chatbot. Know when to bring in a person, and make it easy.
Security and privacy.
Claims files contain some of the most sensitive personal data you hold. Treat access control, encryption and data retention as design requirements.
Change management.
Adjusters who feel threatened will quietly work around the system. Involve them early, retrain them for higher-value work, and be honest about what changes.
Measuring success
Track a small set of numbers honestly: straight-through processing rate, average cycle time, loss adjustment expense per claim, leakage, fraud detection precision, customer satisfaction after claim closure, and reopened claim rate. If speed improves while reopen rates and complaints rise, you have automated the wrong thing.
Where this is heading
The next few years will bring generative AI deeper into the adjuster's day: summarizing long files, drafting customer correspondence, and answering coverage questions against policy language. The carriers that benefit will be the ones with clean data, sound governance and modular systems, not those chasing the newest model every quarter.
Final thoughts
After all these years, my view is simple. AI-powered insurance claims automation is not about replacing people with software. It is about removing the friction that keeps good people from doing good work, and giving customers an answer when they need one most. Start small, protect your data, keep humans in the decisions that matter, and choose partners who understand both the technology and the business of insurance.
If you are planning a claims modernization program and want a candid look at where AI will pay off first in your operation, our team offers software development services, AI development services and insurance-specific engineering to help you get there. Reach out for a discovery conversation.